

Pension plans are meant to create a retirement corpus or help in generating regular income after retirement, and the different types of pension plans differ based on contribution, payout timing, risk, and taxation. From deferred and immediate annuity to NPS, defined benefit, and defined contribution, pension plans allow retirees to choose the type that suits their retirement timeline and needs.
What is Pension Plan?
A pension plan is a financial product that allows an individual to accumulate money during their working period and convert them into regular income after retirement. So, a pension plan definition revolves around the concept of creating a corpus during the earning stage that can be converted into retirement income in the form of lump sum, regular pension, or a combination of the two. In other words, a pension plan helps secure a steady income stream or corpus for the retirement period.
What are the Benefits of Pension Plans for Retirement?
At the time of retirement, a person stops receiving income, but the expenses continue, especially since the average life expectancy is now upwards of 80. Pension plans help in tackling such a scenario because not only do they provide a steady stream of income, converting a part of one’s earnings into retirement income reduces reliance on children and other resources. Additionally, the income from a pension plan is a guaranteed or predictable amount that helps in overcoming inflation and the increased cost of living after retirement.
What are the Different Types of Pension Plans in India?
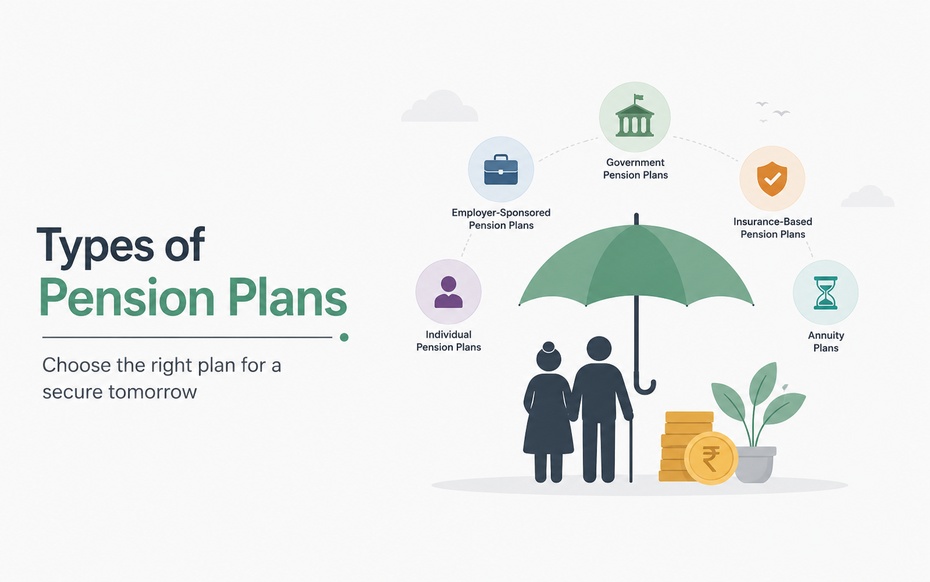
The different types of pension plans in India mostly depend on the point in time when the payout happens after retirement, if any, the investment nature of the plan, the guarantee of payouts upon retirement, as well as the regulating body. Understanding the various categories is essential to compare the types of pension plans on offer and choose one accordingly.
Deferred Annuity Pension Plans
A deferred annuity pension plan is one where an individual pays regular premiums over a period of time, which is then converted into an annuity after retirement. A deferred annuity pension plan, therefore, is beneficial for those with a longer time horizon before retirement as it offers the opportunity to earn on the investments before the payout begins.
Immediate Annuity Pension Plans
An immediate annuity pension plan is one where an investment is made as a lump sum, the annuity payments from which then start immediately or after a short waiting period. Therefore, an immediate annuity pension plan is a better option for those who have decided to retire and require a consistent income stream soon after retirement.
National Pension System (NPS)
The National Pension System is a pension scheme where individuals can contribute a portion of their income to a pension account, which then gets invested in a pension fund. The corpus created is later converted into an annuity based on the withdrawal and pension options chosen at retirement. However, to know more about the withdrawal options, one should look at NPS withdrawal rules instead.
Defined Benefit Pension Plans
A defined benefit pension plan is one where the amount received upon retirement is calculated based on a specific formula, as opposed to being solely dependent on the contributions made and the rate of return earned on them. Defined benefit pension plans are not common for retail investors.
Defined Contribution Pension Plans
A defined contribution pension plan works in contrast to the ones mentioned above. In this case, the contribution made determines the amount upon retirement. As is apparent in the name, a defined contribution pension plan is based on the amount contributed towards the plan and the returns earned on them. The NPS is an example of a defined contribution pension plan.
Pension Plans With Life Insurance Coverage
Many life insurance policies can also be considered pension plans. In such cases, the retirement corpus and the death benefit are separate, with the latter being paid to the nominee if the policyholder dies while the policy is active.
Government-Backed Retirement and Pension Schemes
Besides the ones mentioned above, there are also several government-backed pension schemes, which mostly come under the category of NPS and EPF schemes. These are also long-term plans with features designed to offer retirement benefits while also keeping in mind the regulatory requirements.
How Do Different Types of Pension Plans Compare?
How should one compare the different types of pension plans? Well, it mostly boils down to risk, return on investment (ROI), and liquidity. For instance, deferred annuity pension plans are better for long-term investments and offer better ROI compared to immediate annuity. In turn, guaranteed pension plans, such as those with a fixed payout, offer less ROI than market-linked ones such as the NPS.
Furthermore, liquidity differs significantly between annuity and NPS plans, with the latter offering some flexibility before retirement age while annuity plans do not allow any partial withdrawals.
Which Pension Plan Is Suitable for Different Retirement Needs?
Which pension plan to choose depends on the needs and circumstances of the individual investor. Let’s discuss the different retirement needs and which pension plan types best fulfill them.
People Starting Retirement Planning Early
Young people who are starting their retirement journey should consider deferred annuity pension plans or the NPS because both allow them to make regular contributions for a longer period, which accumulates over time.
People Closer to Retirement Age
On the other hand, individuals who are nearing retirement age and have a lump sum that they wish to convert into a regular income stream should consider an immediate annuity pension plan.
People Wanting Income Stream After Retirement
Annuity-based pension plans, whether immediate or deferred, are ideal for people looking to receive a regular income stream after retirement.
People Wanting Market-Linked Returns
Individuals looking for market-linked returns should consider the NPS or a defined contribution pension plan.
How to Choose the Right Pension Plan
How does one choose a pension plan? What are the deciding factors when choosing a pension plan? The following points can serve as a guide for determining which pension plan will be the most suitable:
• Age and retirement age
• Retirement budget/expenses
• Risk-taking ability
• Current and future income and savings
• Required regular income after retirement
• Liquidity needs after retirement
• Inflation and its impact on future expenses
• Expense ratio, tax implications and charges
How Much Should You Invest for Retirement?
How much one should invest for retirement will mostly depend on:
• Current age and retirement age
• Current expenses and inflation
• Retirement expenses and lifestyle
• Savings profile
• Expected returns from a pension plan
How to avoid mistakes when choosing a pension plan?
When it comes to avoiding errors when choosing a pension plan, a few points should be taken into consideration.
Some of the most common mistakes when choosing a pension plan are:
• Starting retirement planning too late
• Going for a pension plan only for the tax-saving benefits
• Not considering the impact of inflation
• Not going through the fine print of a pension plan, notably the payout options
• Underestimating liquidity needs
• Not considering one’s risk profile
FAQs About Different Types of Pension Plans
1. What are the Different Types of Pension Plans in India?
The different types of pension plans in India are:
-
Deferred annuity and immediate annuity pension plans
-
Pension plans offered under NPS
-
Defined benefit and defined contribution pension plans
-
Insurance-linked pension plans
-
Government-backed retirement schemes
2. What are the Differences between Annuity Plan and NPS?
Annuity pension plans convert a lump sum into regular payouts, while NPS plans are market-linked and allow the corpus to grow before being converted into a regular income stream.
3. Which Pension Plan Helps in Generating Regular Income After Retirement?
Annuity-based pension plans are ideal for retirees looking to receive a regular income after retirement.
4. What are the Differences between Immediate and Deferred Annuity Plans?
Immediate annuity plans allow the payout to begin immediately after purchase, while deferred annuity plans allow the annuity holder to delay the payouts for a specified amount of time.
5. Are Pension Plans Guaranteed?
It depends on the type of pension plan. While annuity-based pension plans are mostly guaranteed, market-linked pension plans such as the NPS are not.
6. Can I Invest in Multiple Different Retirement or Pension Plans?
Yes, it is possible to invest in more than one pension or retirement plan. Investors can choose to diversify their retirement corpus by investing in NPS and an annuity plan.
Disclaimer
Past performance may or may not be sustained in future and should not be used as a basis for comparison with other investments. Returns under NPS are subject to market risk and are prone to fluctuation depending on the state of the Financial market.
Investors are advised to consult their own legal, tax and financial advisors to determine possible tax, legal and other financial implication or consequence of subscribing to the schemes of DSP Pension Fund Managers Private Limited. Tax laws are subject to change.