

Many first-time subscribers search for the NPS lock in period meaning because they assume it works like a fixed deposit's lock-in, when in fact it's tied to your retirement age rather than a fixed number of years.
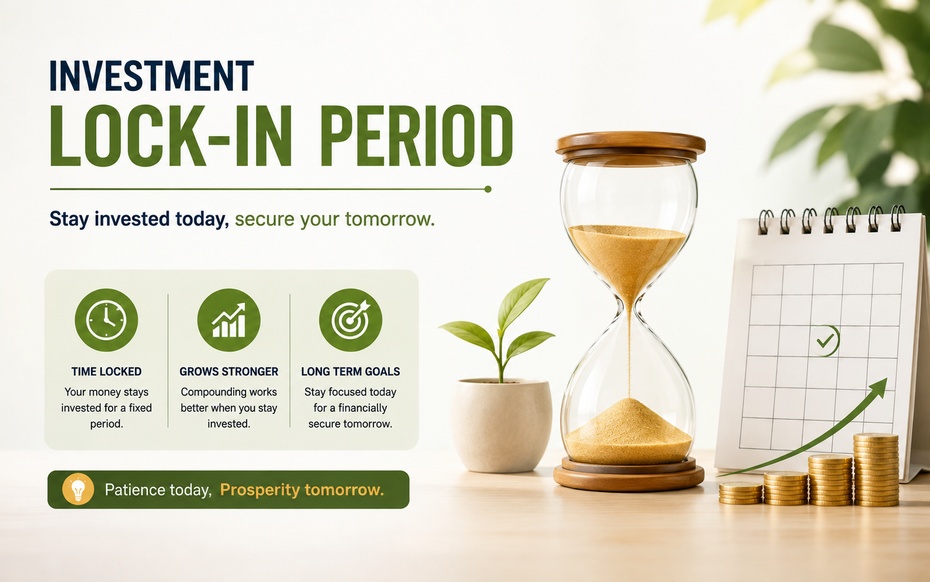
NPS lock in period refers to the minimum period that the subscriber is required to keep his/her contributions locked in before he/she is entitled to withdraw or exit from the account. The lock in period generally applies to Tier I NPS accounts and terminates on reaching 60 years of age or a minimum period of contribution for premature exit, while Tier II NPS account has no lock in period.
What Is Lock in Period for NPS?
NPS lock in period is the minimum period for which the subscriber is required to keep his/her contributions in the account before he/she is eligible to make a withdrawal or claim his/her subscription.
The NPS lock in period exists because NPS is primarily intended for retirement savings and not a savings instrument for the short term, and as such, the contributions are subject to the lock in period before the subscriber can receive the benefits in cash.
However, certain withdrawals are permitted on the grounds of specific events and for the purposes stated by the PFRDA – Pension Fund Regulatory and Development Authority.
NPS Lock In Period for Tier I and Tier II Accounts
There are huge disparities in the lock in period between the NPS Tier I and the NPS Tier II accounts because of their differing objectives.
What is national pension scheme lock in period
NPS Tier I is the retirement savings account that has a lock in period, for which there are specific rules. The NPS Tier I lock in period is generally until the subscriber reaches the age of 60 years or satisfies the minimum period of contribution criteria for premature exit as stipulated for each category of subscriber. The subscriber may, however, make certain withdrawals during this period as stipulated by the PFRDA.
NPS Tier II Lock in Period
The NPS Tier II account has no lock in period because subscribers can make withdrawals of any amount at any time.
How Long Is the NPS Lock in Period?
In short, the NPS lock in period is basically until the subscriber reaches the age of 60 years or satisfies the minimum period of contribution criteria for premature exit as stipulated for each category of subscriber for the Tier I NPS account.
For the most part individual subscribers who fund their accounts on a voluntary basis have a lock in period of 75 percent until at least 60 years of age or a minimum of 15 years from the date of subscription, whichever is later.
This lock in period is for the superannuation or retirement exit option. However, the subscriber may choose to exit from the scheme earlier on a premature exit basis subject to fulfilling eligibility criteria and a more onerous annuitization requirement for a larger portion of the amount withdrawn.
Can You Withdraw Money During the NPS Lock in Period?
Yes, a subscriber can make withdrawals from their NPS Tier I account during the lock in period for specific purposes as determined by the PFRDA. For the most part, NPS provides two withdrawal options during the lock in period namely:
Partial withdrawal: a limited percentage of subscriber’s own contributions for the purposes stated by the PFRDA
Premature exit: closure of subscriber’s NPS account prior to eligibility for superannuation on meeting certain conditions and subject to higher annuitization requirements.
Partial Withdrawal During the NPS Lock In Period
Partial withdrawal is basically a limited withdrawal facility that allows a subscriber to withdraw a restricted percentage of subscriber’s own contributions (excluding employer/optional contributions) for specific purposes such as marriage, medical treatment, children’s education, house construction, or business purpose.
Premature Exit From NPS
Unlike partial withdrawal, premature exit entails withdrawal of the subscriber’s entire contribution from the NPS before retirement age. Subscribers can exit prematurely from the NPS scheme under certain conditions stipulated by the PFRDA after completing a minimum lock in period. A higher percentage of the withdrawal is subject to annuitization upon premature exit in order to ensure that the subscriber has sufficient retirement benefits.
Partial Withdrawal vs Premature Exit From NPS
Partial withdrawal is different from premature exit in various ways. The differences between partial withdrawal and premature exit are discussed below.
Partial withdrawal Vs. Premature exit
The core difference lies in what happens to your account. In a partial withdrawal, the account continues, only a limited amount tied to your own contributions is withdrawn, and specific eligible purposes apply.
In a premature exit, the account is closed altogether, a much larger share of the total corpus may need to go into an annuity, and the remaining retirement corpus is reduced meaningfully compared to waiting until normal retirement.
Tax Treatment of NPS Withdrawals and Maturity
Is NPS withdrawal taxable? The taxability of NPS withdrawals is as follows: the lump sum withdrawal at the maturity is tax-free up to a limit while the corpus used to buy the annuity is not taxed at the time of withdrawal; however, the pension income from the annuity is taxable.
With regards to partial withdrawal, the amount withdrawn is generally tax-free subject to certain conditions and as stipulated by the income tax laws.
However, the taxation rules may differ depending on various criteria. It is advisable to consult the most recent tax rules before making a withdrawal or upon maturity.
What Happens to Your NPS Corpus at Retirement?
Upon retirement or superannuation of the subscriber or upon his/her premature exit based on the conditions discussed earlier, the subscriber’s corpus upon maturity will be split into two parts as follows:
Lump-sum withdrawal: this is a tax-free withdrawal that is limited to a certain percentage of the subscriber’s contribution depending on the total corpus value
Annuity purchase: is a mandatory purchase of an annuity using at least the minimum percentage of the subscriber’s corpus. Generally, at least 40 percent of the subscriber’s corpus upon maturity is used to buy an annuity.
Things to Consider Before Withdrawing From NPS Early
The decision to partially withdraw from NPS should be considered based on the following factors:
Considerations
Having less money for retirement may result in lower future pension if the lump sum withdrawal upon maturity is not enough; a smaller investment of the total contributions will result in a smaller pension
Earlier withdrawal may reduce the lump sum upon maturity because of the shorter contribution period
Partial withdrawals should be a recourse for unforeseen personal financial distress and not for convenience purposes.
FAQs About NPS Lock in Period
1. Does NPS have a lock in period like the ELSS fund or a 5-year tax-saving fixed deposit?
NPS is primarily a long-term retirement savings instrument and as such has a lock in period for Tier I contributions as discussed earlier. For this reason, NPS is not comparable to other short term tax-saving instruments like ELSS or a 5-year tax-saving FD.
2. Does NPS Tier II account have a lock in period?
NPS Tier II account does not have a lock in period for any contributions made to it. The subscriber can withdraw any amount at any time.
3. Can the NPS account be continued beyond retirement age?
Yes, subscriber can continue to contribute until a certain age or defer withdrawals from NPS beyond the normal retirement age as stipulated by the NPS rules.
4. What is the difference between partial withdrawal and premature exit from NPS?
Partial withdrawal from NPS allows a permanent withdrawal of a limited percentage of subscriber’s own contributions while premature exit allows the subscriber to permanently withdraw the entire amount contributed to his/her NPS account before retirement age subject to annuitization of a larger percentage of the withdrawal.
5. What happens to my NPS upon leaving my job?
The subscriber’s NPS account and PRAN are portable. In other words, upon resignation or changing jobs, the subscriber can easily continue contributing to his/her existing NPS account regardless of the type of employment.
Disclaimer
Past performance may or may not be sustained in future and should not be used as a basis for comparison with other investments. Returns under NPS are subject to market risk and are prone to fluctuation depending on the state of the Financial market.
Investors are advised to consult their own legal, tax and financial advisors to determine possible tax, legal and other financial implication or consequence of subscribing to the schemes of DSP Pension Fund Managers Private Limited. Tax laws are subject to change.